Cap rate: the price of the income stream
The capitalization rate is the simplest of the three: net operating income divided by price. A property producing $1,100,000 of NOI at an $18,000,000 price trades at a 6.11% cap. The figure involves no leverage and no forecast, just this year’s unlevered income yield.
That simplicity is the point. Cap rate is the market’s common currency: it lets you compare a deal in Tampa against one in Phoenix in a single number, and it’s how your exit gets valued: the buyer in year five will pay your stabilized NOI divided by whatever cap rate the market demands then. It also leaves out leverage, capital expenditures, growth, and every year after the first.
Direction matters more than magnitude: caps compressing (falling) means values rising for the same income; caps expanding means the reverse. Underwriting an exit cap below your going-in cap is a bet that the market will pay more per dollar of income in five years, which is purely a bet on timing.
IRR: the price of time
The internal rate of return is the annualized rate that discounts every cash flow (equity out on day one, distributions along the way, sale proceeds at exit) back to zero. It is the only metric of the three that accounts for when money moves, which is why institutional LPs anchor on it and why waterfall hurdles are written in IRR terms.
Its weakness is the same sensitivity: IRR can be flattered without making anyone richer. A cash-out refinance in year two that returns half the equity early can push IRR up several points while total profit barely moves. Two deals with identical 17% IRRs can return very different amounts of cash, which is exactly the blind spot the equity multiple covers.
Equity multiple: the price of the whole ride
The equity multiple (MOIC) is total cash returned divided by total cash invested. Put in $5,600,000, get back $11,700,000 across the hold — that’s a 2.09× multiple. It ignores timing completely, which makes it the honest counterweight to IRR: nobody engineers a multiple with a refi. A 2.0× over five years and a 2.0× over ten years are the same multiple but wildly different annual returns, which is why neither metric stands alone.
One deal, three lenses
The 120-unit example from our underwriting guide carries an $18.0M purchase, 65% leverage, a five-year hold, and sale at a 6.25% exit cap:
Same deal, three answers
Read together, they answer the three questions an investment committee actually asks: whether the price is fair for the income (cap rate), whether the return is worth the hold (IRR), and whether the absolute profit is worth the effort (multiple).
Where each one misleads
- Cap rate misleads on growth. A 5-cap with rents 20% under market can be cheaper than a 6-cap at full market. It also says nothing about leverage: the same 6-cap deal produces very different equity returns at 50% vs 70% LTV.
- IRR misleads on scale and timing. Early distributions inflate it; a small, quick deal can post a dazzling IRR on trivial profit. Always ask what the multiple was.
- Equity multiple misleads on time. 2.0× sounds great until you learn it took eleven years. Always ask what the IRR was.
- All three mislead when the inputs do. Every metric is downstream of the rent roll, the T-12, and the expense normalization. Garbage in, confident-looking garbage out.
Quote all three, always
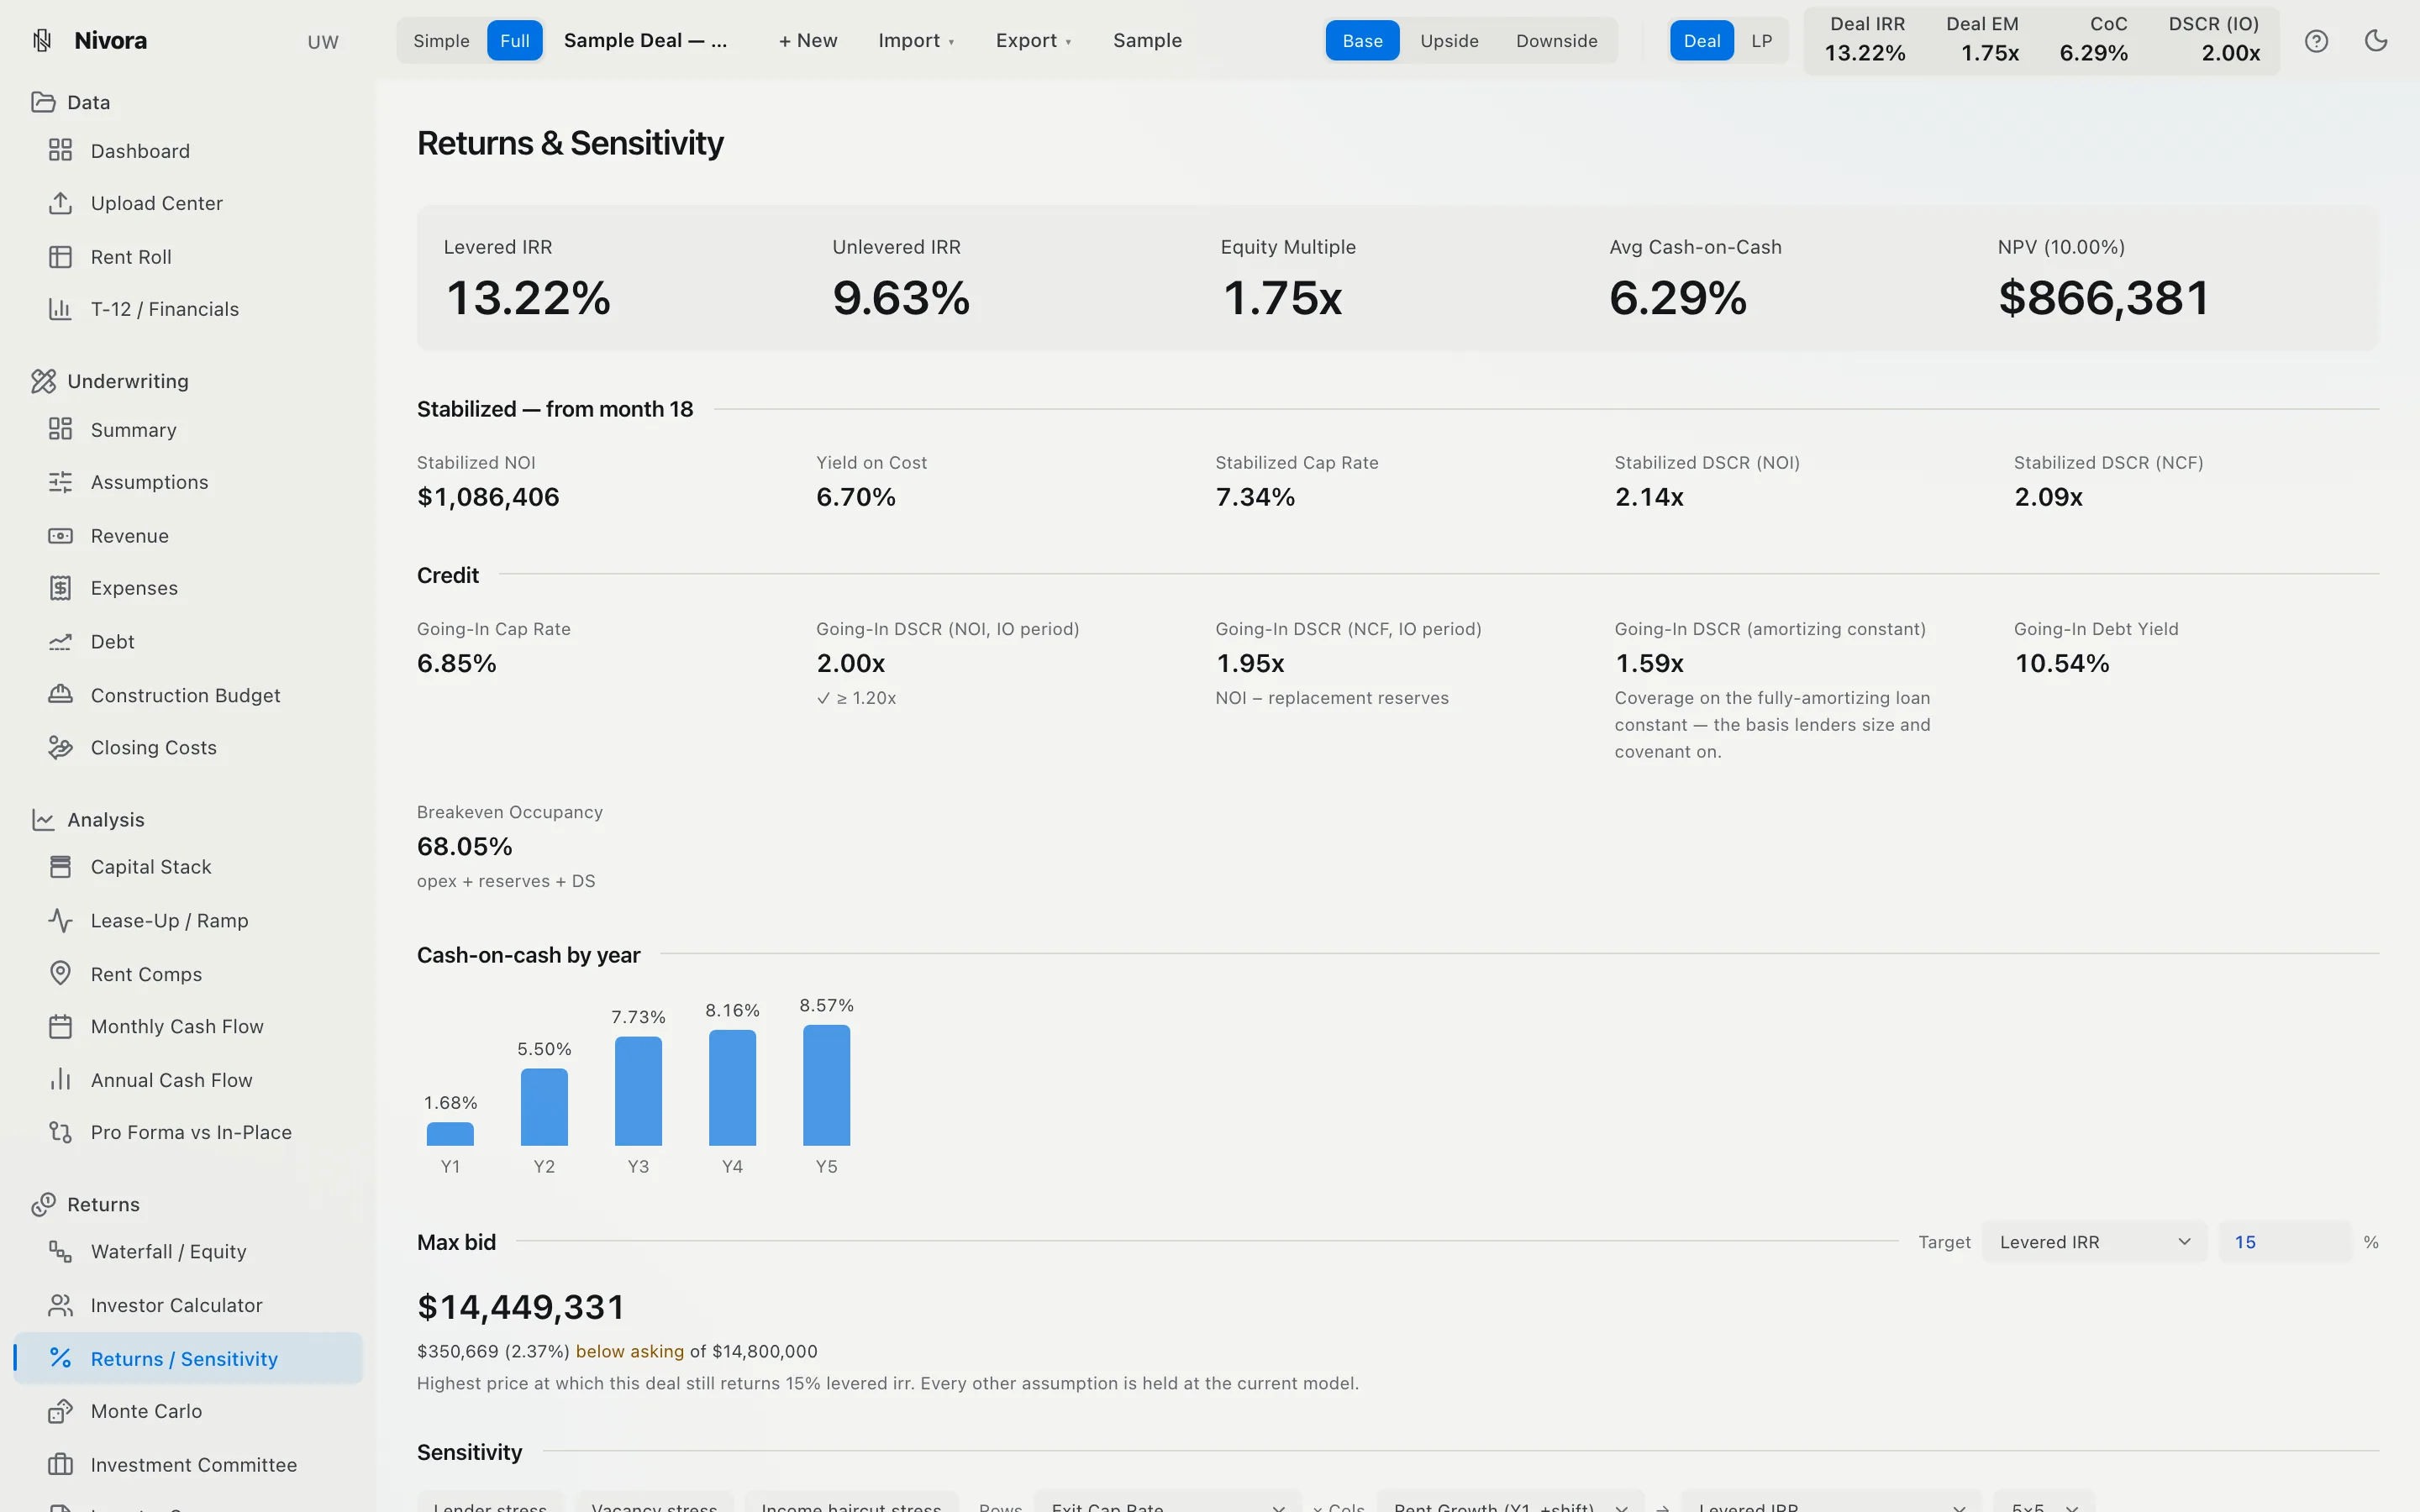
The discipline is simple: never present one without the others, and never compute them by hand twice. In Nivora, IRR (deal-level and LP-level), equity multiple, cash-on-cash, and the full cap-rate picture are computed from the same monthly cash-flow model and reconciled against each other on every change, so the three lenses can never quietly drift apart in separate spreadsheet tabs. If you just want the cap rate on a deal right now, try the free cap rate calculator.
Frequently asked questions
What is the difference between cap rate, IRR, and equity multiple?
Cap rate prices the asset: this year’s net operating income divided by price, with no leverage and no forecast. IRR prices the time: the annualized return that accounts for when every dollar goes in and comes out. The equity multiple prices the total ride: total cash returned divided by cash invested, ignoring timing. Each leaves out something the other two show.
How is cap rate calculated?
Cap rate = net operating income ÷ purchase price. A property producing $1,100,000 of NOI at an $18,000,000 price trades at a 6.11% cap rate. Because it uses one year of unlevered income, it says nothing about leverage, capital expenditures, or growth.
What does IRR measure in real estate?
IRR is the annualized rate that discounts every equity cash flow (the investment on day one, distributions along the way, and sale proceeds at exit) back to zero. It is the only one of the three metrics that accounts for timing, which is why waterfall hurdles are written in IRR terms, and also why early distributions or a cash-out refinance can raise it without adding much profit.
What is an equity multiple?
The equity multiple (also called MOIC) is total cash returned divided by total cash invested. It ignores timing completely: a 2.0× multiple over five years and a 2.0× multiple over ten years are very different annual returns. That is why it is read alongside IRR, never instead of it.
Which return metric matters most?
None of them alone. Cap rate answers whether the price is fair for the income, IRR answers whether the return is worth the hold, and the equity multiple answers whether the absolute profit is worth the effort. Serious underwriting quotes all three, computed from the same cash-flow model.
See it computed live.
Every concept on this page is a number Nivora computes live: the real engine is running on a fictional 104-unit sample deal right now, no login required.